
Last Updated: 23 October 2026
Quick Summary
FCA compliance for foreign financial firms means meeting the FCA’s authorisation, conduct and reporting standards before serving UK customers. Passporting ended for most firms after Brexit, so the FCA expects overseas applicants to evidence UK-specific systems and controls from day one.
- The FCA assesses whether your firm can be supervised effectively, not whether you are well regulated at home.
- The overseas persons exclusion is narrow and rarely covers direct marketing to UK retail clients.
- Section 21 requires authorisation or an authorised approver before marketing reaches UK recipients.
- Regulatory reporting applies from authorisation day and must reconcile with your UK entity’s records.
- Submitting a home-market business plan with cosmetic edits is the most common application failure.
Table of Contents
- FCA Compliance for Foreign Financial Firms: What Changes When You Cross the Border
- Do You Need FCA Authorisation for Overseas Firms, or Does the Overseas Persons Exclusion Apply?
- The FCA Compliance Checklist for International Firms Entering the Market
- UK Financial Promotion Rules for Overseas Firms: The s21 Gateway Explained
- FCA Regulatory Reporting Requirements for International Firms
- How the FCA Supervises International Firms: Threshold Conditions and the Supervision Process
- Common Mistakes Foreign Firms Make in FCA Applications
- Frequently Asked Questions
FCA Compliance for Foreign Financial Firms: What Changes When You Cross the Border
FCA compliance for foreign financial firms is the process of meeting the Financial Conduct Authority’s authorisation, conduct and reporting standards before serving customers in the UK. It is not a translation of your home regulator’s rulebook. Passporting ended for most firms after Brexit, and the FCA now expects overseas applicants to evidence UK-specific systems and controls from day one.
That is the part most guides get wrong. They treat cross-border authorisation as a paperwork exercise. The FCA treats it as a supervisory question: can this firm be supervised effectively from outside the UK, and will it treat UK customers fairly?
At FCA Authorisation, we have worked on regulatory submissions since 2000. Firms that map their home processes onto the FCA’s threshold conditions, rather than copying their home rulebook, move through the gateway faster.
Below, we break down what actually changes when you cross the border, from the overseas persons exclusion to the s21 financial promotion gateway, plus the checklist we would use ourselves.
The single most important shift for overseas firms is this: the FCA assesses whether you can be supervised, not whether you are already well regulated elsewhere. Build the application around that question.
Do You Need FCA Authorisation for Overseas Firms, or Does the Overseas Persons Exclusion Apply?
The overseas persons exclusion is narrow, and most firms that assume it covers them are wrong. It applies to specific activities carried out with or through UK-authorised firms, not to a general permission to market to UK retail clients.
Under the Regulated Activities Order, the exclusion can cover certain transactions with or through authorised persons, and limited overseas activity. It does not give you a licence to onboard UK customers directly. If you are soliciting UK clients, holding their money, or managing their investments from abroad, you are likely carrying on regulated activity in the UK and need authorisation.
The practical test we apply is simple: who is the client, where is the activity performed, and who bears the risk? If the answer points to UK clients and UK-facing conduct, the exclusion rarely helps.
- Direct marketing to UK retail clients: authorisation normally required
- Dealing with UK clients through a UK-authorised counterparty: exclusion may apply
- Managing investments for UK clients from an overseas office: authorisation normally required
- Pure reverse solicitation: fact-specific, and the FCA scrutinises claims closely
The FCA’s approach to international firms sets out how the regulator treats firms without a UK establishment. Read it before you decide the exclusion applies to you.
The FCA Compliance Checklist for International Firms Entering the Market
An FCA compliance checklist for international firms should start with the threshold conditions, because every application is tested against them. Work through this before you draft a single page of the application.
- Identify every regulated activity you will carry on in the UK and map it to the correct permission
- Confirm your legal structure and whether you need a UK establishment
- Appoint Senior Management Functions, including a SMF16 compliance oversight and SMF17 money laundering reporting officer where required
- Document your governance map, including reporting lines into the overseas parent
- Write a bespoke regulatory business plan covering the first three years
- Set out your financial resources and wind-down planning
- Evidence your systems and controls: complaints handling, financial crime, outsourcing and record keeping
- Prepare the change in control notifications if your ownership structure triggers them
- Confirm your regulatory reporting capability before go-live
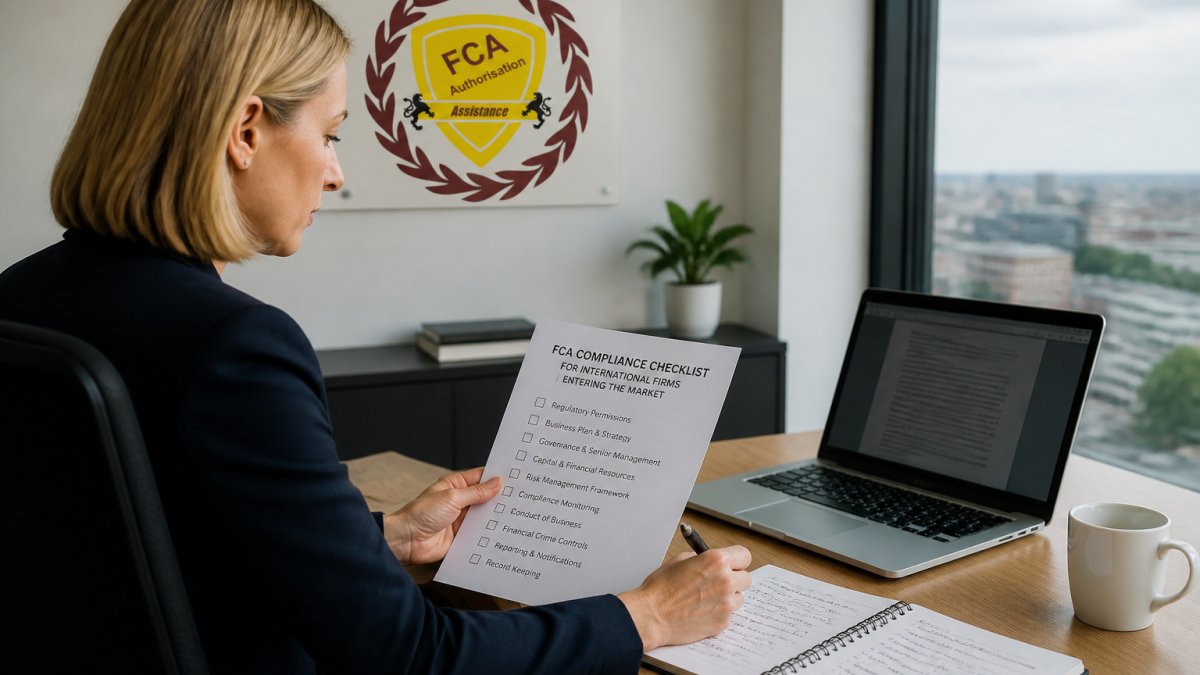
The most common failure we see is a firm submitting its home regulator’s business plan with the name changed. The FCA’s reviewers spot this quickly, and it triggers questions that delay the application by months.
UK Financial Promotion Rules for Overseas Firms: The s21 Gateway Explained
UK financial promotion rules for overseas firms hinge on section 21 of the Financial Services and Markets Act 2000. In simple terms, a firm must not communicate an invitation or inducement to engage in investment activity unless it is authorised or the content is approved by an authorised person (Financial Services and Markets Act 2000).
For an overseas firm, this is the gateway that catches most people out. You can be fully regulated in your home market and still breach s21 the moment your marketing reaches UK recipients without an authorised approver in place.
The exemptions exist, but they are technical. The financial promotion order contains categories for high-net-worth individuals, sophisticated investors and certain overseas communications. Relying on them without advice is risky, because the burden sits with you to show the exemption applied.
Our view: if UK growth is the plan, get authorised or get an approver. Do not build a marketing strategy on an exemption you cannot document.
FCA Regulatory Reporting Requirements for International Firms
FCA regulatory reporting requirements apply from the day you are authorised, and they do not flex for overseas parent structures. You will need to submit regular returns through the FCA’s systems, and the data must reconcile with your UK entity’s records, not your group’s consolidated figures.
Expect to report on capital adequacy, client money where relevant, complaints, and conduct metrics. The reporting calendar is fixed, and late submissions are visible to supervisors.
Two practical points we raise with every international client. First, confirm who signs off returns and whether that person sits in the UK or overseas, because accountability must be clear. Second, test your reporting pipeline before authorisation, not after. Firms that discover a data gap in month one start their supervisory relationship on the back foot.
The FCA’s regulatory reporting guidance lists the returns that apply by permission type. Match your permissions to the reporting set early.
How the FCA Supervises International Firms: Threshold Conditions and the Supervision Process
Supervision of international firms runs through the same threshold conditions as domestic applicants, with extra attention to whether the firm can be supervised effectively. The FCA will look at your group structure, your home regulator’s standing, and whether information flows to the UK are reliable.
In practice, this means your application should address supervision directly. Show how the FCA will get timely information, who in the UK is accountable, and how you handle a supervisory request that arrives on a Friday afternoon.
Firms with a clear UK presence and named accountable individuals tend to have smoother supervision. Firms run entirely from overseas, with no local decision-making, face more questions about how UK customers are protected when something goes wrong.
Name a UK-based point of contact with real authority in your application. It is a small detail that changes how supervisors read the rest of your submission.
Common Mistakes Foreign Firms Make in FCA Applications
The mistakes repeat. After extensive application experience, we can predict many common mistakes.
- Submitting a home-market business plan with cosmetic edits
- Underestimating the s21 financial promotion gateway and marketing before authorisation
- Naming Senior Management Functions without evidencing their actual responsibilities
- Treating the overseas persons exclusion as broader than it is
- Leaving reporting capability untested until after go-live
- Failing to explain how the overseas parent’s decisions reach the UK entity
Each one costs time. Some cost the application.
If you have been rejected once, the fix is not a resubmission with more documents. It is a diagnostic: identify which threshold condition the FCA doubted, then rebuild the evidence around that specific point. That is the approach we take with clients who come to us after a refusal.
Overseas firms with a UK growth plan and no local compliance team, who need the application built and project-managed end to end rather than assembled in-house.
Frequently Asked Questions
Do foreign financial firms need FCA authorisation to operate in the UK?
It depends on the activity and the client. A foreign firm needs FCA authorisation if it carries on a regulated activity by way of business in the UK, unless a specific exclusion applies. The overseas persons exclusion can cover certain dealings with professional or institutional counterparties, but it does not cover retail clients. Firms relying on the exclusion should document why it applies to each activity, because the FCA will ask for that reasoning during supervision.
Can an overseas financial firm provide services to UK customers without FCA authorisation?
Only in narrow circumstances. Marketing to UK retail clients, holding client money, or advising on investments generally requires authorisation or an appointed representative arrangement. The financial promotion gateway under section 21 of FSMA also catches overseas firms communicating invitations or inducements to UK clients. If you are unsure whether your model crosses the line, take advice before you market, not after, because unauthorised activity is a criminal offence and can bar future applications.
What should a foreign firm include in its FCA compliance programme?
At minimum: a documented governance structure with clear SMF accountabilities, a compliance monitoring plan, financial crime controls including AML and sanctions screening, a complaints procedure, and records showing how you meet the threshold conditions. Add a training log and a regulatory change log. The FCA expects the programme to be proportionate to your UK activity, so a firm with a small UK book does not need the same infrastructure as a UK bank, but it must be able to evidence every control it claims to run.
How do UK financial promotion rules apply to overseas firms?
Any invitation or inducement to engage in investment activity communicated to a UK person must be made or approved by an authorised person, unless an exemption applies. The section 21 gateway applies regardless of where the communicator sits, so an overseas firm marketing into the UK is caught. The exemptions are narrow and fact-specific, and the FCA has been clear that offshore location is not itself a defence. Review every client-facing communication, including websites and social media, before launch.
What ongoing FCA regulatory reporting requirements apply to international firms?
Reporting depends on permissions and legal structure, but most authorised firms submit regular returns through the FCA’s online system, including financial data, complaints data, and, where relevant, prudential returns. Firms must also notify the FCA of changes in control under section 178 of FSMA and of any matter that could affect the threshold conditions. Late or inaccurate returns are a common supervisory finding, so build a reporting calendar with named owners and test it before your first submission.
How does the FCA supervise international firms operating in the UK?
The FCA supervises on a portfolio basis, grouping firms by the harm their activities could cause. International firms typically sit in a portfolio matched to their UK permissions rather than their home regulator. Supervision includes periodic information requests, firm meetings, and thematic reviews, plus reactive work when a risk emerges. Firms should expect the supervisor to test whether the UK operation is genuinely controlled from the UK, so governance and local accountability need to be real, not nominal.
Cross-border authorisation is not a harder version of a domestic application. It is a different one, and the FCA reads it that way. If you want the process handled by people who have sat across the table from the Authorisations team since 2000, FCA Authorisation offers bespoke application packs, fixed project costs and full project management from inception to completion. Get started with FCA Authorisation and move into the UK market with a submission built to survive scrutiny.
